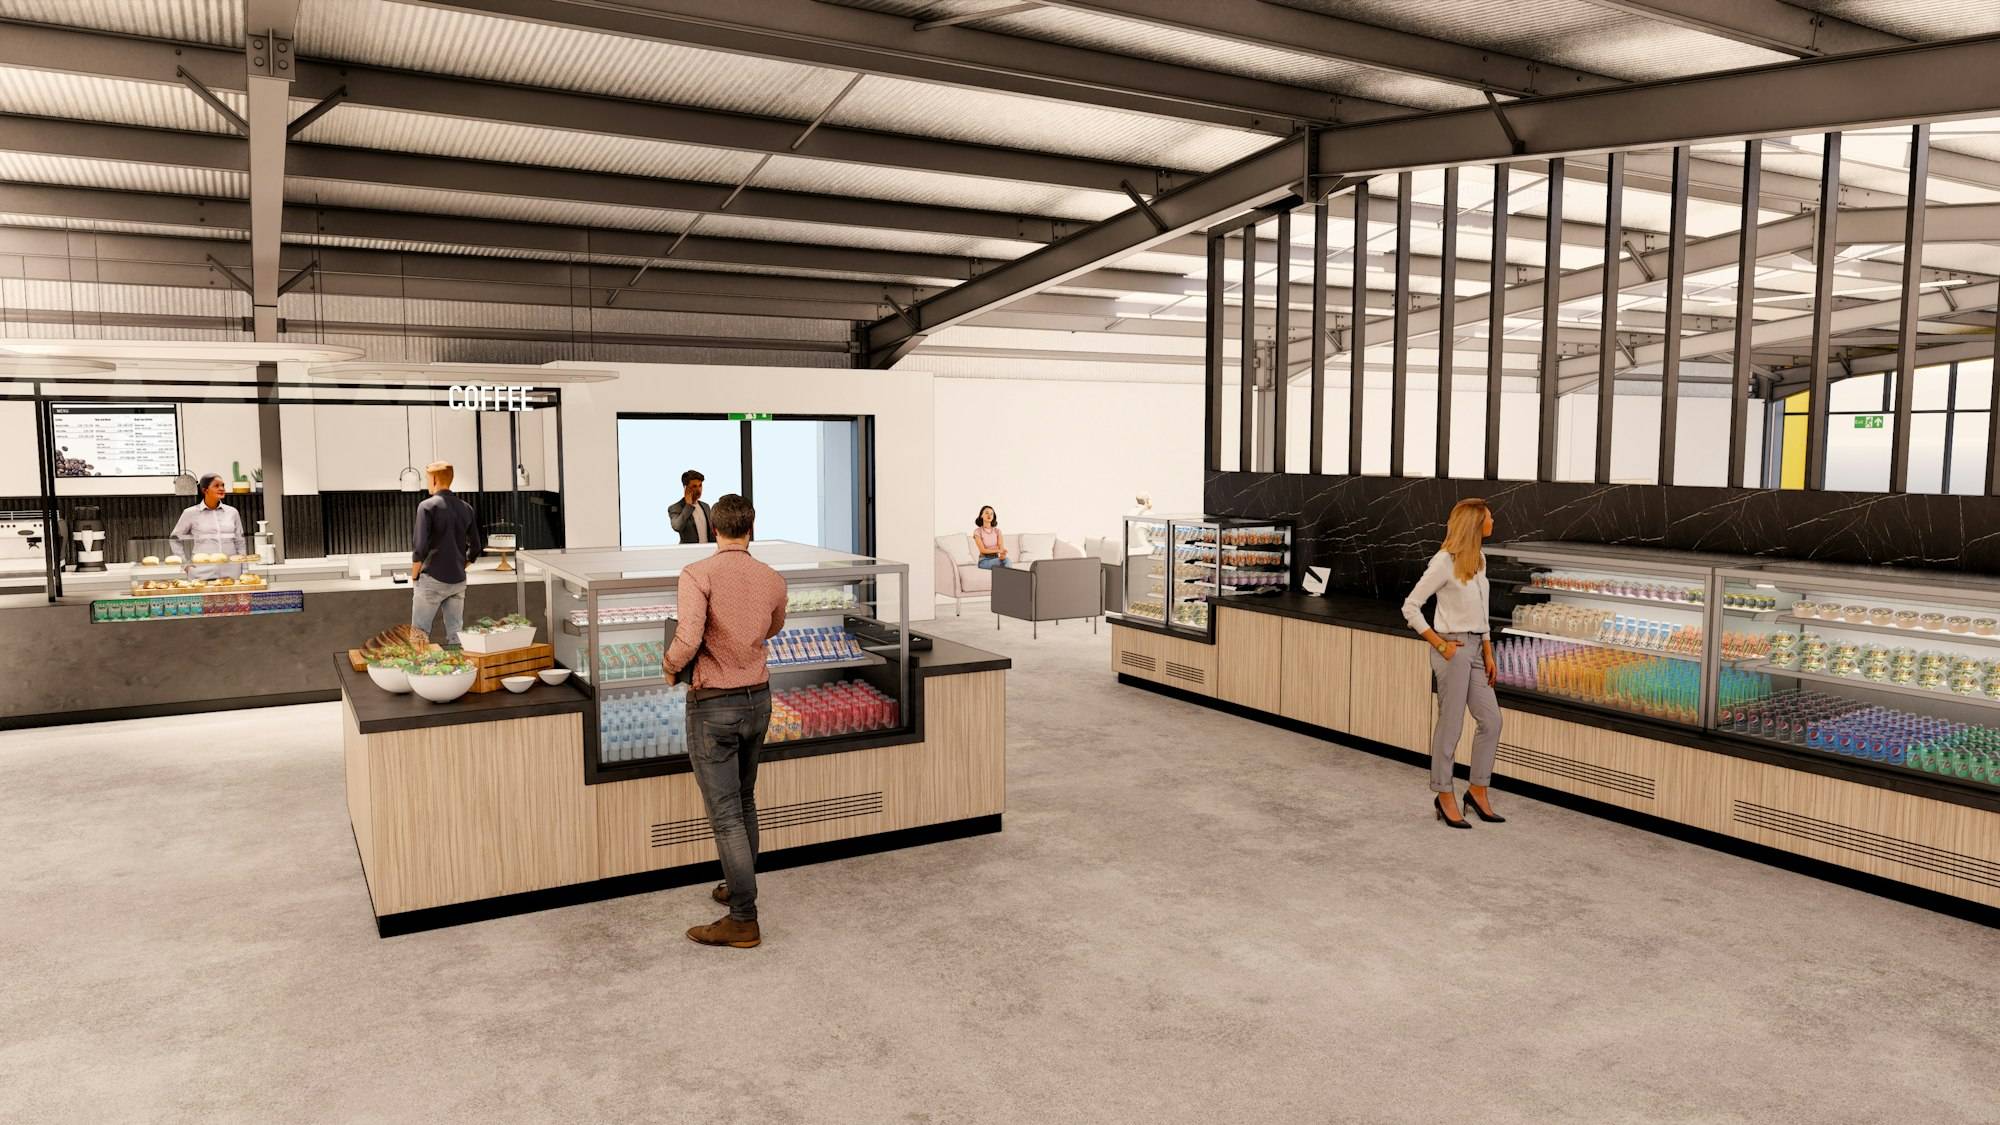
A new site is one of the biggest bets a small business makes: a second cafe in Hamilton, a bigger clinic in Tauranga, a showroom in Christchurch, a proper workshop instead of the garage. The fit-out is where the money goes — and where budgets tend to blow out.
Why is fit-out funding different?
Most lenders don’t treat a fit-out as security. Once joinery is built, plumbing is run and a counter is installed for a specific tenancy, it has almost no resale value. If the business fails, the lender can’t take the fit-out away and sell it.
So fit-outs are usually funded in one of two ways:
1. A property-secured loan. Equity in New Zealand property — your home, a rental, commercial property or land — secures a loan from $20,000 to $1m as a first or second mortgage. The property provides the comfort, so the fit-out doesn’t need to. No financials or tax returns are needed for the initial assessment.
2. An unsecured business loan sized to your existing turnover. If your current business has been trading 6+ months with healthy bank statements, a cash flow lender may fund part or all of the fit-out based on what the business already earns. This works best for expansions — a second site — rather than a first site with no trading history.
Movable equipment within the fit-out — commercial kitchen gear, chillers, salon chairs, vehicles — can sometimes be financed separately against the equipment itself. See our answer on funding equipment and vehicles.
How much will the fit-out really cost?
Fit-out budgets have a habit of growing. Before you ask for a number, build the full picture:
- Design and consents. Designer or architect fees, and council building consent if structural, plumbing or drainage work is involved.
- The build. Builder, joiner, electrician, plumber, painter, flooring, signage.
- Services. Upgrading power, gas, extraction, fire systems or accessibility to current code.
- Equipment and furniture.
- Tech. EFTPOS, POS, networking, security.
- Contingency. Allow a meaningful buffer for surprises — old buildings in particular reveal things once walls come off.
- Working capital. Rent on the new site before it opens, wages for staff hired early, opening stock, and marketing.
Our guide to working out how much to borrow helps you add it up so you ask once, not twice.
What lenders will want to know
- The lease. Term, rights of renewal, rent, any landlord contribution or rent-free period, and who owns the fit-out at the end (check the make-good clause).
- Quotes. From your builder and main trades.
- Timeline. When the build starts and when you’ll open.
- The plan. For a second site, what the first site does; for a relocation, why the new site will lift revenue.
- Repayment. Trading surplus from the new site, the existing business, or both.
Structure repayments around the opening date
A new site rarely makes money in its first few weeks. Talk to your specialist about structuring the funding so repayments are realistic during the ramp-up. Property-secured loans are typically short to medium term, and a common plan is to refinance to a bank once the new site has a year of trading behind it.
Check the lease before you borrow
The single biggest risk in fit-out funding isn’t the loan — it’s a lease that doesn’t give you long enough to earn back the investment. If your lease has three years left and no right of renewal, a large fit-out is hard to justify. Get legal advice on the lease before committing to the build.
What does it cost?
Every loan is priced on the individual situation — security, trading history and amount. We’ll look across our lending partners for the sharpest available option for your circumstances and explain the total cost up front.
Ready to build?
Get your quotes and lease terms together and ring the Hotline. A specialist will help you work out the right amount and structure. Or request a call back.